Understanding Reverse Mortgages
Reverse mortgages have become a significant financial tool for seniors seeking to unlock the equity in their homes. These loans allow older homeowners to convert part of their home equity into cash without requiring monthly mortgage payments. As you navigate this financial option, it's essential to understand the mechanics, benefits, and potential drawbacks involved. The landscape of reverse mortgages has evolved, especially with recent economic changes, making it more crucial than ever to stay informed.
What are Reverse Mortgages?
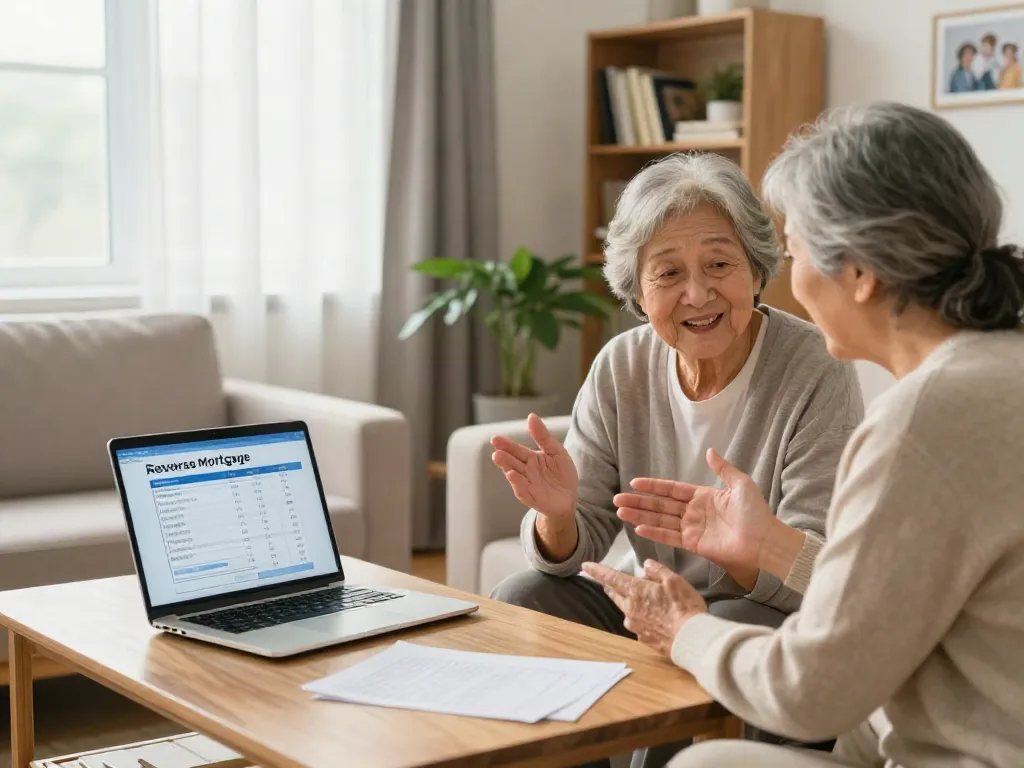
A reverse mortgage is a type of loan available primarily to homeowners aged 62 and older, enabling them to borrow against the equity in their home. Unlike traditional mortgages where homeowners make monthly payments to lenders, reverse mortgages allow homeowners to receive payments and defer repayment until they sell the home, move out, or pass away. The most common type of reverse mortgage is the Home Equity Conversion Mortgage (HECM), backed by the government and subject to specific regulations.
How Do Reverse Mortgages Work?
The mechanics of reverse mortgages involve converting the homeowner's equity into cash, which can be disbursed in various ways, including a lump sum, monthly payments, or a line of credit. The loan amount is determined by several factors, including the homeowner's age, the home's value, and prevailing interest rates. Homeowners continue to hold title to their homes, meaning they are still responsible for property taxes, insurance, and maintenance. The loan is repaid when the homeowner no longer occupies the property, ensuring flexibility and control over their financial situation.
Common Misconceptions about Reverse Mortgages
Many misconceptions cloud the understanding of reverse mortgages. Some believe that taking out a reverse mortgage means losing ownership of their home, which is not true. Others worry about the risk of owing more than the home's value. However, with reverse mortgages, if the home sells for less than the loan amount, borrowers are protected from deficiency judgments due to non-recourse provisions. Understanding these facts can help homeowners make informed decisions.
Benefits of Reverse Mortgages
Accessing Home Equity for Financial Flexibility
One of the primary attractions of reverse mortgages is the ability to access home equity without the need for monthly payments. This financial flexibility can be particularly beneficial for retirees on fixed incomes. Homeowners can use the funds for various purposes, such as covering healthcare expenses, home renovations, or simply enhancing their quality of life.
Improving Retirement Cash Flow
For many seniors, retirement income may not suffice to cover rising living costs. Reverse mortgages can provide an additional stream of income, helping to improve cash flow. This can ease financial stress, allowing retirees to enjoy their golden years without the constant worry of monthly mortgage payments.
Tax-Free Funds for Seniors
Funds received from a reverse mortgage are generally tax-free, as they are considered loan proceeds rather than income. This characteristic allows seniors to access additional cash without impacting their tax situation, making reverse mortgages an attractive option for funding healthcare, vacations, or other lifestyle desires.
Eligibility and Requirements
Who Qualifies for a Reverse Mortgage?
To qualify for a reverse mortgage, homeowners must meet specific criteria. They need to be at least 62 years old, have sufficient equity in their home, and occupy the home as their primary residence. Additionally, potential borrowers must demonstrate the financial capacity to maintain the property, including paying property taxes, insurance, and upkeep costs.
Necessary Documentation and Application Process
The application process for a reverse mortgage involves several steps, including an assessment of the homeowner's financial situation and home value. Necessary documentation typically includes proof of age, income verification, and details about the property. Homeowners must also undergo mandatory counseling from an approved HUD counselor to ensure they fully understand the implications of the loan.
Factors That Affect Eligibility
Several factors can affect eligibility for a reverse mortgage, including the home's appraised value, the borrower's credit history, and the current interest rates. A lower interest rate can increase the amount available to borrow, while a higher home value can also significantly improve borrowing potential. Understanding these factors can help homeowners better prepare for the application process.
Potential Downsides of Reverse Mortgages
Understanding the Costs Involved
While reverse mortgages offer many benefits, they also come with costs that borrowers must consider. These costs may include origination fees, closing costs, and mortgage insurance premiums. Additionally, interest accrues over time, increasing the total amount owed when the loan comes due. It's crucial for borrowers to weigh these costs against the potential benefits.
Impact on Heirs and Estate Planning
One significant downside of reverse mortgages is their potential impact on heirs. As the loan amount increases, the equity in the home decreases, which can affect what heirs inherit. It's essential for homeowners to discuss these implications with their family members and include them in estate planning conversations.
Common Risks of Reverse Mortgages
Like any financial product, reverse mortgages carry inherent risks. Homeowners could find themselves in financial trouble if they fail to keep up with property taxes, insurance, and maintenance costs. Additionally, drastic changes in housing market conditions could affect property value, impacting the amount available through a reverse mortgage. Awareness of these risks can facilitate more informed decision-making.
Future Trends in Reverse Mortgages
The Evolving Landscape for Seniors in 2026
The landscape of reverse mortgages is poised for significant changes by 2026, with an increasing number of seniors looking to leverage their home equity. As the aging population grows, financial institutions may adapt to meet the needs of these homeowners by introducing more flexible products and terms. The demand for innovative financial solutions is expected to rise as retirees explore ways to optimize their financial situations.
Innovative Products Emerging in the Market
New products that blend traditional mortgages with reverse mortgages are emerging, providing homeowners with greater flexibility. These offerings may include features that allow for more control over withdrawals or repayment plans that cater specifically to varied financial scenarios. As these innovations come to market, they could change the perceptions and uptake of reverse mortgages.
Challenges and Opportunities for Financial Advisors
Financial advisors will play a pivotal role in guiding seniors and their families through the complexities of reverse mortgages. They must navigate the challenges posed by potential changes in regulations and market dynamics while simultaneously leveraging opportunities to educate clients about the benefits and risks involved. By staying informed, financial professionals can help their clients make sound decisions regarding reverse mortgages.
What is the downside of getting a reverse mortgage?
The downsides of reverse mortgages often revolve around costs, impact on estate inheritance, and the risk of losing the home if financial obligations are not met. It is essential for potential borrowers to engage in thorough research and consider their long-term financial goals.
What does Suze Orman say about reverse mortgages?
Financial expert Suze Orman has expressed concerns about reverse mortgages, particularly emphasizing the importance of understanding the long-term implications and costs involved. She advises homeowners to approach reverse mortgages with caution and to consider their full financial picture before proceeding.
What is the 60% rule in reverse mortgage?
The 60% rule is a guideline pertaining to how much of the loan proceeds can be accessed in the first year. Under this rule, borrowers can only access 60% of the loan's value in the first 12 months if the funds are used for specific purposes, such as paying off an existing mortgage or certain necessary expenses. Understanding this rule is critical for effective financial planning.
What disqualifies you from getting a reverse mortgage?
Several factors can disqualify a borrower from obtaining a reverse mortgage, including insufficient home equity, failure to meet the minimum age requirement, and a poor credit history. Additionally, if the homeowner does not occupy the property as their primary residence, they may be ineligible for a reverse mortgage.